

Shareholders of Carriage Services would probably like to forget the past six months even happened. The stock dropped 29% and now trades at $32.89. This was partly due to its softer quarterly results and may have investors wondering how to approach the situation.
Is now the time to buy Carriage Services, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Do We Think Carriage Services Will Underperform?
Even with the cheaper entry price, we’re passing on Carriage Services for now. Here are three reasons we avoid CSV, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
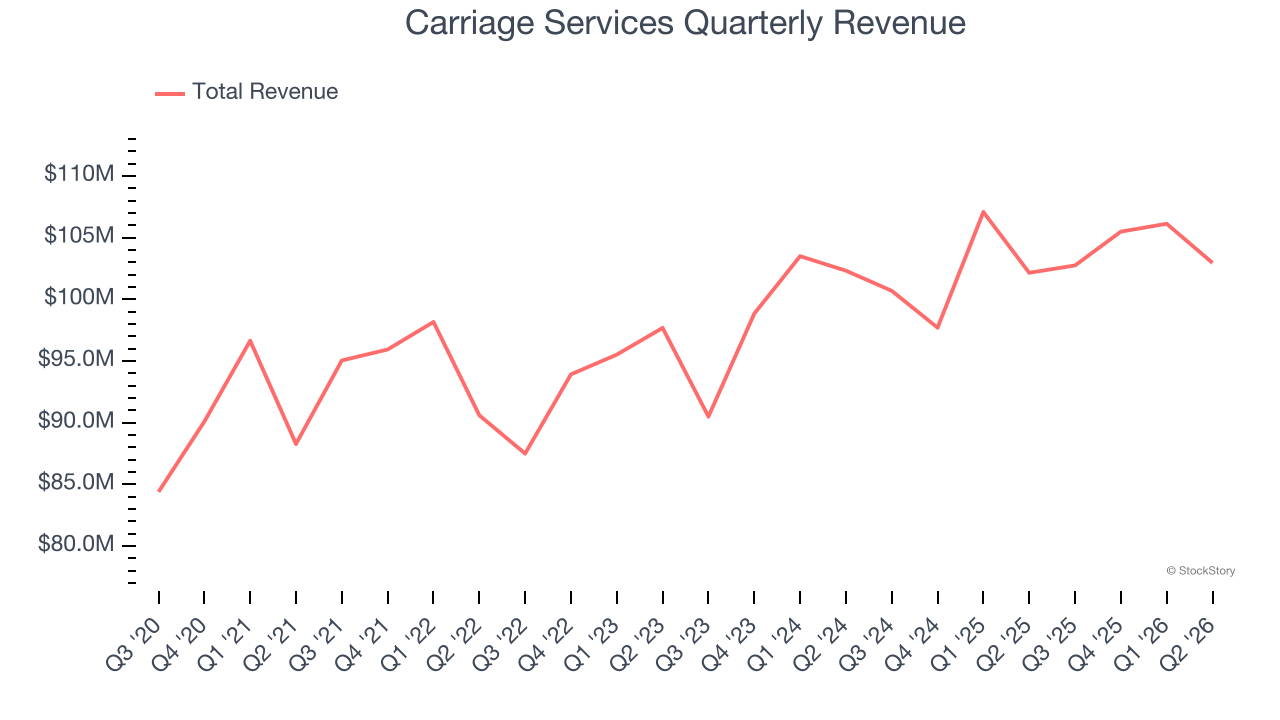
Examining a company’s long-term performance can provide clues about its quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Over the last five years, Carriage Services grew its sales at a weak 3% compounded annual growth rate. This was below our standard for the consumer discretionary sector.
2. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
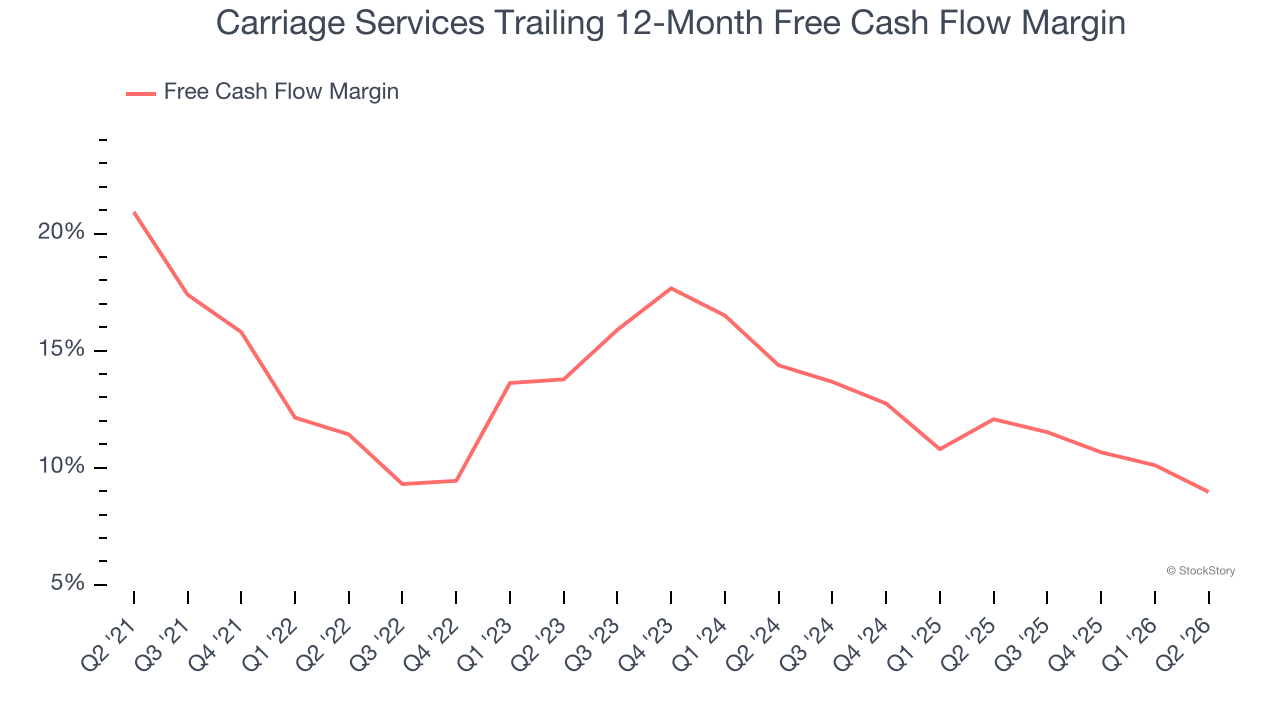
Carriage Services has shown poor cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 10.5%, below what we’d expect for a consumer discretionary business.
3. New Investments Aren’t Moving the Needle
We like to invest in businesses with high returns, but the trend in a company’s ROIC can also be an early indicator of future business quality.
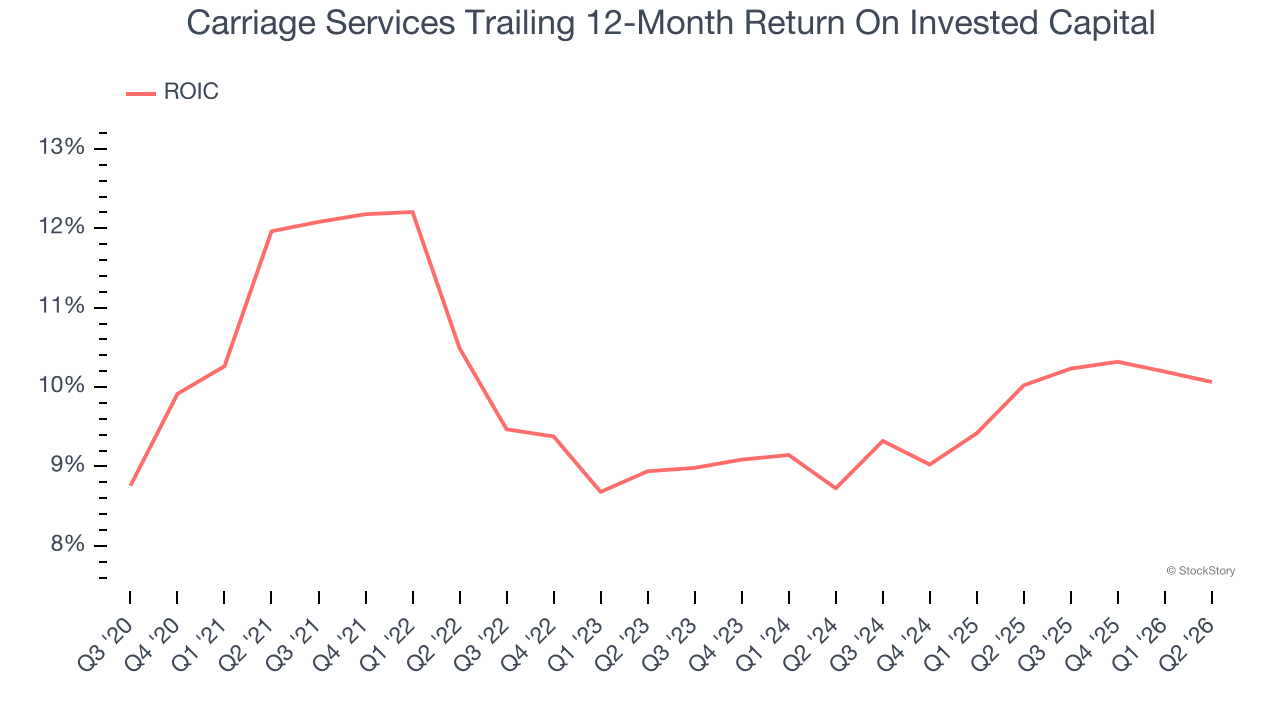
Unfortunately, Carriage Services’s ROIC has stayed the same over the last few years. If the company wants to become an investable business, it must improve its returns by generating more profitable growth.
Final Judgment
We cheer for all companies serving everyday consumers, but in the case of Carriage Services, we’ll be cheering from the sidelines. After the recent drawdown, the stock trades at 9.3× forward P/E (or $32.89 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are better investments elsewhere. We’d suggest looking at one of our all-time favorite software stocks.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.